When a business needs funds, the first question is usually what the money is for. The purpose often points to the right type of finance. Two of the most common options are a business loan and working capital finance, and they serve quite different needs.
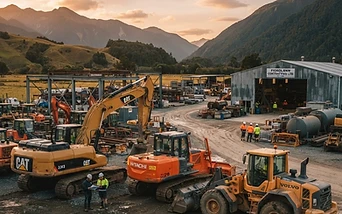
A business loan is typically a lump sum borrowed for a specific, often larger, purpose. This might be purchasing equipment, buying a vehicle, or funding an expansion. The loan is repaid over a set term with regular payments, and the asset being purchased often acts as security.
Working capital finance, on the other hand, is designed to bridge short-term gaps between money going out and money coming in. It can help cover wages, rent, or supplier invoices while you wait for customer payments. Facilities are often flexible, letting you draw down what you need and repay as cash flow allows.
A useful rule of thumb is to match the life of the asset to the life of the finance. Long-term purchases like trucks or machinery suit term loans. Short-term needs like stock or wages suit working capital. Using a long-term loan to cover a short-term gap can leave you paying for something long after the need has passed.
Cost is another difference. Working capital facilities may have higher ongoing costs if used continuously, while term loans usually have a fixed repayment schedule that is easier to budget around. The right choice depends on how predictable your revenue is and how quickly the funds will generate a return.
If you are unsure which fits your situation, a broker can help you weigh up both. At Loan Link we listen to what the funds are for, then present options from several lenders so you can compare them side by side.